Opening a business account can take minutes for the customer and hours for the compliance team. That gap explains much of what is broken in B2B onboarding today.
The customer experience has become digital, but many internal AML processes still depend on analysts moving between data providers, reviewing documents, investigating shareholders and ultimate beneficial owners, screening for PEPs and sanctions, evaluating alerts, and ultimately deciding whether a company should be onboarded.
That process is not necessarily bad. The problem starts when volume grows. A hundred new businesses a month may be manageable with a strong team. Ten thousand require a different architecture.
The answer is not simply to “automate AML,” either. Fintechs need to separate what can be decided deterministically from what genuinely requires investigation and human judgment.
The best AML automation does not remove compliance analysts. It removes the work that never needed a compliance analyst in the first place.
That distinction matters.
Business onboarding is about much more than verifying a company
Consumer onboarding largely revolves around one individual. Business onboarding becomes more complex very quickly.
A fintech needs to understand not only whether a company exists, but who sits behind it. That can involve validating corporate information, registration status, business activity, incorporation date, address, shareholders, directors, and ultimate beneficial owners (UBO).
Then comes the second layer: risk.
- Is any shareholder or UBO a politically exposed person (PEP)?
- Are there matches against sanctions lists or watchlists?
- Are there material adverse signals?
- Does the company's stated activity make sense for the product it is applying for?
- Does the ownership structure warrant further investigation?
- Are there inconsistencies between what the customer declared and what external sources show?
The real challenge in KYB is not retrieving a piece of data: it is connecting multiple signals and turning them into a consistent decision.
Where does time disappear in a manual AML review?
Consider a fairly typical workflow: an analyst checks corporate records, identifies shareholders, determines beneficial owners, screens relevant individuals through another provider, checks PEP and sanctions data, reviews risk signals, and compares everything against internal policy. If an alert appears, the analyst investigates, then documents the conclusion.
Now multiply that process by hundreds or thousands of applications. Cost is only part of the problem.
Two analysts can interpret the same situation slightly differently. Turnaround times increase during periods of high demand. And a policy that is perfectly clear in a compliance manual can still be applied inconsistently in day-to-day operations.
Automation starts here: turning AML policy into an executable decision flow.
1. Turn AML policy into rules
Many compliance policies are still written for humans to interpret. For example: “Businesses whose ultimate beneficial owners are identified as PEPs must undergo enhanced due diligence.”
To automate it, policy needs to become operational logic:
UBO identified → PEP screening → confirmed match → Enhanced Due Diligence / manual review.
Another example: “Businesses operating in higher-risk industries require additional review.” That becomes:
Business activity → risk classification → high risk → request additional info + route to review.
This exercise is fundamental. Before buying more data or adding AI to the process, a fintech needs to know what it intends to decide with each signal.
2. Automate data collection
Once the policy is structured, data becomes the next bottleneck: corporate records, ownership structures, UBO information, PEP databases, sanctions lists, watchlists, adverse media, fraud signals, documents, and internal data.
In a manual process, every lookup becomes another task. In an automated flow, the system receives a company identifier and automatically runs the checks required by policy.
Crucially: not every company needs the same checks. Straightforward companies can follow one path, while complex or higher-risk profiles trigger progressive diligence only when risk justifies it.
3. Automate shareholder and UBO screening
Approving a company without understanding who controls it leaves a fundamental part of risk unassessed. A decisioning infrastructure needs to understand relationships:
Company → shareholders → ultimate beneficial owners → directors.
The output should not simply be a collection of API responses: the platform needs to interpret those responses within policy. A potential PEP match does not mean automatic rejection — it may trigger an Enhanced Due Diligence path.
Screening is not decisioning.
Checking a list is screening. Determining what should happen because of the result is decisioning.
4. Build an onboarding risk score
When evaluating dozens of variables, consolidating signals into risk classifications accelerates decisioning:
- Low Risk: straightforward ownership, expected activity, no material alerts → straight-through approval.
- Medium Risk: signals requiring additional validation → simplified review or document request.
- High Risk: combination of PEP exposure, sanctions, complex structure or jurisdiction → Enhanced Due Diligence (EDD).
5. Automate the obvious. Send exceptions to people.
A fintech should not try to automate every case: it should automate every case where a person adds no meaningful value.
Clear passes are approved automatically. Clear policy violations are rejected automatically. Human judgment is reserved for the ambiguous middle ground.
At Sinky, a workflow built in Studio routes these exceptions directly into AI Case Management, where analysts receive pre-assembled dossiers with relevant evidence and third-party data organized.
6. Use AI where it actually makes sense
Some decisions must remain deterministic. AI delivers real value by handling tedious cognitive overhead: extracting document data, comparing declared info with uploads, identifying inconsistencies, and summarizing complex files.
Example of AI-generated case brief:
“The company was routed to review because of a potential PEP match involving one of its ultimate beneficial owners. Corporate registration data is consistent with the information provided. No material matches were found in the other screenings performed. Validation of the potential PEP match is recommended before onboarding continues.”
7. Make every decision explainable
Automating a regulated decision without explaining how it happened trades operational friction for regulatory vulnerability. Decisioning infrastructure must preserve versioning, audit trails, and input/output snapshots so fintechs can answer not just why an account was approved, but why it was approved under the exact policy active at that date.
8. AML does not end when onboarding ends
A low-risk business today may change directors, add shareholders, or see an owner become a PEP six months from now. Onboarding policy should evolve into continuous monitoring rules, automated re-screening, and active risk alerts.
What architecture does a fintech need to automate AML?
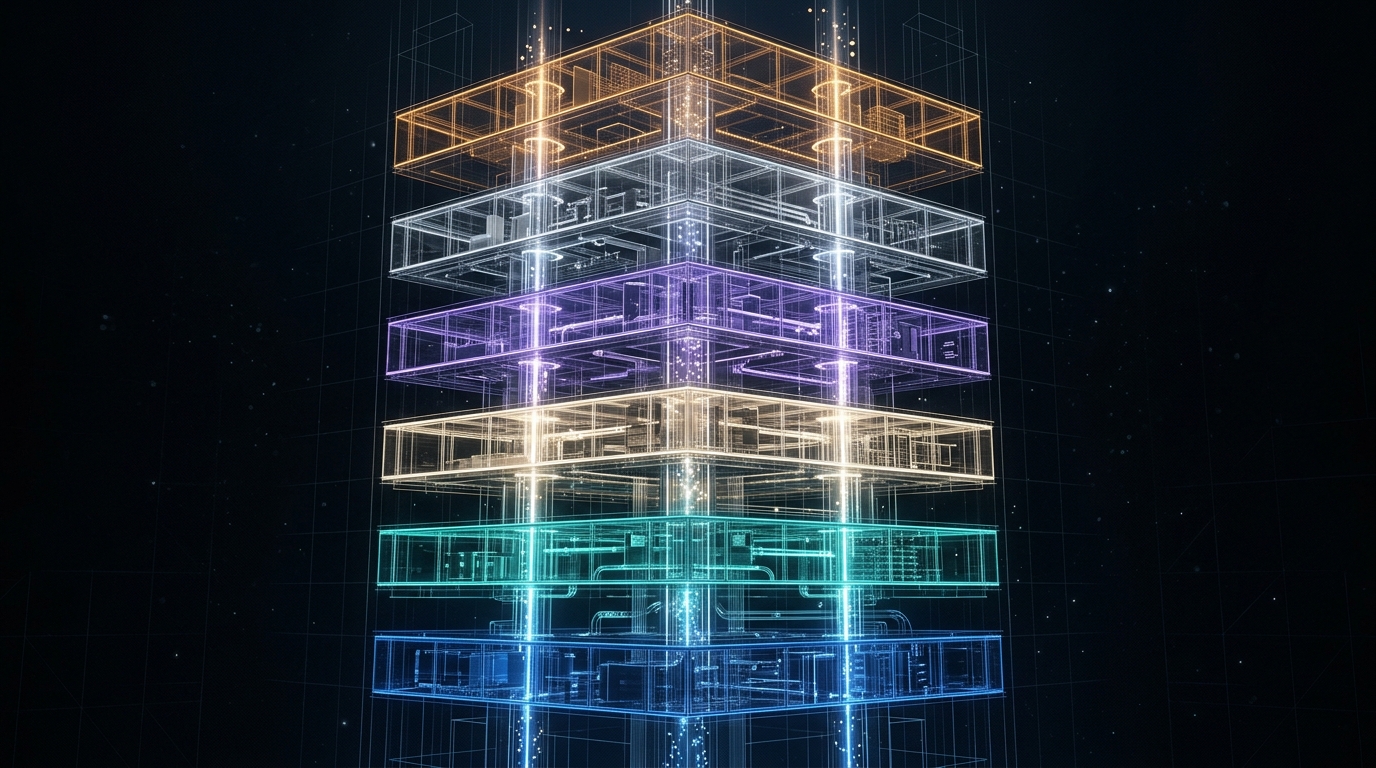
Modern compliance decisioning requires four coordinated layers:
- Data: corporate records, UBO, PEP, sanctions, watchlists, fraud signals, internal data.
- Decisioning: policies, rules, scores, workflows, thresholds, and escalation logic.
- Case Management: exception workflows, human review, SLAs, and decision capture.
- Monitoring: re-screening, corporate registry diffs, and ongoing risk re-scoring.
Where does Sinky fit?
Sinky connects specialized data providers into a unified decisioning infrastructure. With Sinky Studio, compliance teams visually construct onboarding flows, test rules, integrate providers via the Data Marketplace, and dispatch complex cases directly into AI Case Management.
Machines execute policy. People focus on the exceptions that require judgment.